Microsoft: A good time to invest?
In today’s world there are many viable strategies that financial managers adhere to when it comes to creating and protecting wealth for their clients. Investors and economists alike have debated the viability of various investment philosophies over the years and the truth is, there is no consensus as to which one of the myriad of methods of investing that we see employed in today’s market is the absolute best. This is the beauty of the market; success can be found in any ways, shapes, and forms. Yet, one of the most common phrases you will hear when listening to discussions about portfolio management is “diversification”.
This is a core concept of modern investing that helps to spread risk around, providing investors with exposure to a multitude of asset classes and asset types which come together to form a broader basket that have the potential to perform well, regardless of the broader economic environment and sentiment facing the market.
Within the equity space, specifically, you’ll often hear about different sector and industry allocation targets within a well diversified portfolio. You’ll also hear discussions about different subsets of equities, such as growth stocks, value stocks, defensive stocks, dividend stocks, etc. All of this can be intimidating.
Truth be told, the variety that exists in the market leads to another common phrase that we hear, which is “paralysis by analysis”, meaning that oftentimes, when faced which such a wide variety of options, investors freeze up, fail to capitalize on attractive opportunities that the stock market provides, and ultimately underperform.
However, all of this discussion about diversification leads us back towards one of the most talked about stocks in the market today: Microsoft (MSFT).
In recent days there have been dozens of articles, blog posts, and analyst reports published concerning this company. And, as our algorithm broke down the data, we found a consensus forming amongst 4 and 5-star analysts within the Nobias tracking system. Although Microsoft shares have not been isolated from the recent sell-off in the NASDAQ, with its share falling roughly 6.5% during the last week, there’s do doubt that sentiment is positive when it comes to the long-term prospects of this company. 70.3% of the reports we analyzed carried a bullish opinion. And, a prevailing theme amongst those articles was that the size and scope of Microsoft’s operations make this a stock that can fit into a wide array of investment strategies, meaning that there are very few limitations on the types of buyers who would be interested in owning MSFT stock.
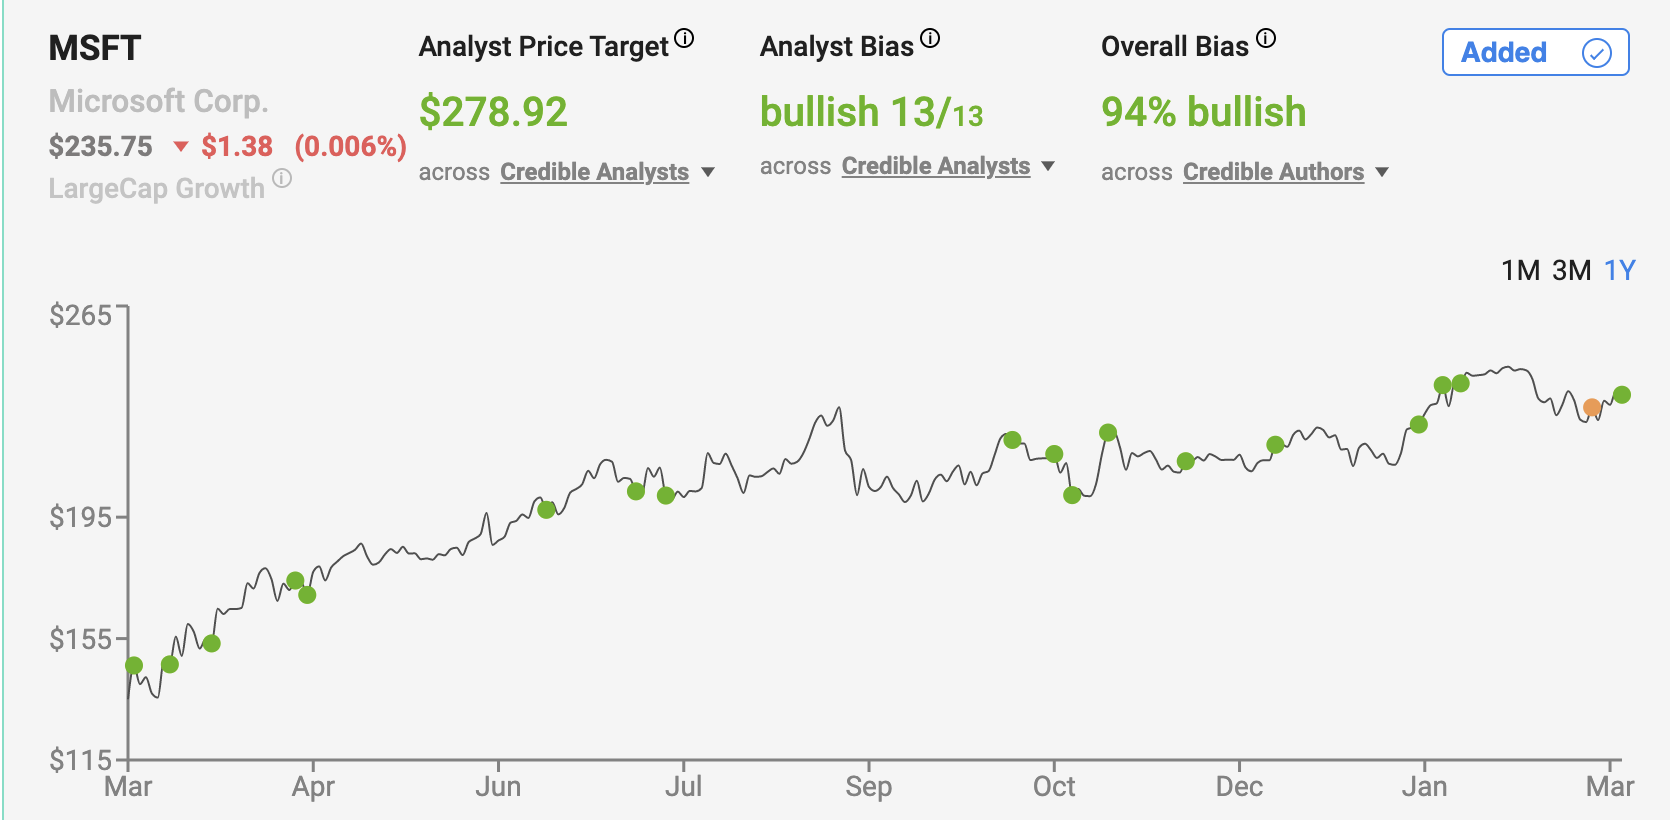
Why is there such broad demand for shares of this $1.79 trillion company?
Well, as Wayne Duggan, a 5-star Nobias analyst who contributes to InvestorPlace put it in his recent article “4 Reasons To Love Microsoft Stock” this company benefits from secular growth in multiple ways. First and foremost, Duggan highlights the double digit revenue growth that Microsoft is generating with its cloud services. During Microsoft’s most recent quarter, the company’s “Intelligent Cloud” segment posted sales of $14.6 billion, which beat analyst estimates of $13.75 billion anad represented a year-over-year growth rate of 23%. Microsoft’s Azure cloud platform saw revenue growth of 50% during the quarter, which was an acceleration compared to the 48% growth during the prior reporting period. This strong cloud growth helped to propel the company’s overall revenue growth to 17% during the quarter.
But, as Duggan puts it, it’s not just about top-line growth. He says: “But all revenue is not created equal. Azure’s revenue is the good kind of revenue. Not only does Microsoft’s cloud sales have higher margins than its overall business, but the unit’s margins are expanding over time. As cloud revenue accounts for more and more of Microsoft’s overall revenue each quarter, it raises Microsoft’s overall profitability.”
And, speaking of demand that creates a situation where not only sales, but also prices rise (which translates into attractive margins), Duggan points out that Microsoft’s Office 365 subscriptions grew 15% on a year-over-year basis last quarter, while posting an average sale price that was 5% higher as well. Duggan quoted John Freeman, a Microsoft analyst at CFRA, who said, “Office, ~22% of [total] revenue, [is] benefiting from a cloud shift tailwind kicking in now that Office 365 cloud subscriptions are 2x+ license/support revenue,” Freeman says. CFRA is projecting Office 365 will help Microsoft more than double its 2019 EPS by 2023.”
The next major secular growth theme that Microsoft benefits from is gaming. The gaming industry has been on the rise for years now as technology in the space progresses; however, during the COVID-19 pandemic, social distancing, which bolstered the stay-at-home economy, has turned digital gaming into one of the world’s premiere segments of the border media/entertainment market. And, as Duggan Points out, Microsoft offers investors a leadership position in this industry, with its Xbox platform. Duggan notes that Microsoft has acquired 6 different gaming studios in recent years and the company’s Xbox Game Pass subscription service now has more than 18 million members. “In fact,” he says, “Microsoft reported 3 million new subscribers in its most recent reported quarter alone. Xbox’s content and services revenue was up 40% year-over-year in the quarter.”
And lastly, we arrive at social media, which is an industry that Microsoft entered in 2016 with its $26.2 billion acquisition of LinkedIn. Unlike other social media platforms, which have been mired with social and political headwinds, LinkedIn, which focuses purely on enterprise communications, has provided Microsoft with less volatile exposure to the growing market. Duggan says that “the platform has become a business-to-business marketing hub, and LinkedIn’s talent solutions (recruiting) business is now a major revenue source.”
What’s more, Duggan expects that LinkenIn will continue to provide Microsoft with opportunities to upsell users its enterprise software solutions. He notes that LinkedIn generates more than double the average revenue per user (ARPU) than peers Twitter (TWTR) and Snap (SNAP).
And, it appears that Microsoft’s appetite for social media exposure has not yet been satiated. Recent reports have risen regarding rumors that Microsoft management has held talks to acquire Pinterest (PINS). Danny Vena of The Motley Fool recently reported that while talks here have reportedly stalled, it’s clear that Microsoft is interested in the space.
Vena notes that Microsoft expressed interest in taking over TikTok’s U.S. operations last year when the Trump administration threatened to ban the app domestically due to digital security concerns. He goes on to say, “It's easy to see why Microsoft might be interested in adding another top-flight social network. Since acquiring LinkedIn, estimated revenue from the professional networking app has nearly quadrupled to more than $8 billion in 2020, though Microsoft doesn't break out its results.”
The primary concern that Duggan brings up is Microsoft’s valuation. He says that “Microsoft stock trades at 34.7 times the company’s trailing earnings and 31.75 times its forward earnings.” This ~35x blended price-to-earnings multiple is well above MSFT’s 20-year average P/E ratio of 21.1x. Yet, the high growth and similarly high margins associated with Microsoft’s growing software-as-a-service (SaaS) business appear to justify the high premium in analysts' eyes.
Duggan concludes his article, saying, “Now may not be the best time to buy MSFT stock for a quick trade. However, long-term investors who buy any dips can sleep well at night.” Duggan’s colleague at InvestorPlace, Dana Blankenhorn, who also happens to be a 5-star Nobias analyst, recently covered Microsoft’s cloud success as well, saying, “Microsoft’s global cloud is now a fully realized profits juggernaut.”
Yet, Blankenhorn also noted MSFT’s high valuation, saying “as the market turns toward value Microsoft doesn’t provide it. The price to earnings ratio is near 35x. A 56 cent per share dividend that once seemed generous now yields less than 1%.” But, much like Duggan, even with his valuation based caution in the short-term, Blankenhorn maintained a long-term bullish outlook, saying, “All 23 following it on Tipranks have it on their buy lists. Their average one-year price targets are 21% ahead of where it’s currently trading. You can buy Microsoft “on the dip” and look good in five years. I’m not selling my little stake.”

Nicholas Ward is a Senior Investment Analyst at Wide Moat Research. He has spent the last 8 years writing about the stock market at various publications, including Seeking Alpha, The Street, Forbes Real Estate Investor, Sure Dividend, The Dividend Kings, iREIT, Safe High Yield, and The Intelligent Dividend Investor.
Other analysts share a similar opinion. For instance, Billy Duberstein, of the Motley Fool, recently highlighted Microsoft in his article “Got $5000? 3 Tech Stocks To Buy And Hold For The Long-Term”. Duberstein touched upon Microsoft’s growth rates in the cloud and gaming segments and then he highlighted the company’s bottom-line success, saying, “Even more impressive, margins expanded, with operating income up 29% and earnings per share up 34% year-over-year. Even at an expensive-looking 34 times earnings, Microsoft's 34% EPS growth still gives it a PEG ratio of 1, which could actually be considered cheap!”
The most cautious stance that we came across from within the 5-star Nobias community, was published by David Van Knapp of Daily Trade Alert. However, even while presenting a cautious approach due to valuation, he still called Microsoft his “High Quality Dividend Growth Stock Of The Month” saying: “This month’s pick, Microsoft (MSFT), is in pretty much the same boat. Its rich valuation means that I would not recommend its purchase at the moment for most investors.
That said, some investors, especially younger ones, may not care much about current valuations, because in 10-15 years, they won’t care what they paid for the best companies; they will just be glad that they own them.”
Disclosure: Nicholas Ward is long shares of Microsoft. Nicholas Ward wrote this article for Nobias at their request with a view of giving investors a balanced perspective based on the writings of Nobias highly rated analysts and bloggers. Nobias has no business relationship with any company whose stock is mentioned in this article and does not have a position in this stock.
Additional disclosure: All content is published and provided as an information source for investors capable of making their own investment decisions. None of the information offered should be construed to be advice or a recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. The information offered is impersonal and not tailored to the investment needs of any specific person.
Disclaimer: The Nobias star rating is based on past performance results and is not an indicator of future results. These past performance returns do not represent returns that any investor actually earned. Assumptions made include the ability to purchase the stocks recommended by the author under liquid markets where the transaction would be at the market price for the day. In reality, loss in liquidity may have a material impact on the returns that actually may have been earned. Further, returns are calculated without any including transaction costs, management fees, performance fees or expenses, or reinvestment of dividends and other income. This information is provided for illustrative purposes only.